Brick, Mortar, and Riyal: How US Investors Are Tapping Saudi Arabia's Real Estate Financing Revolution
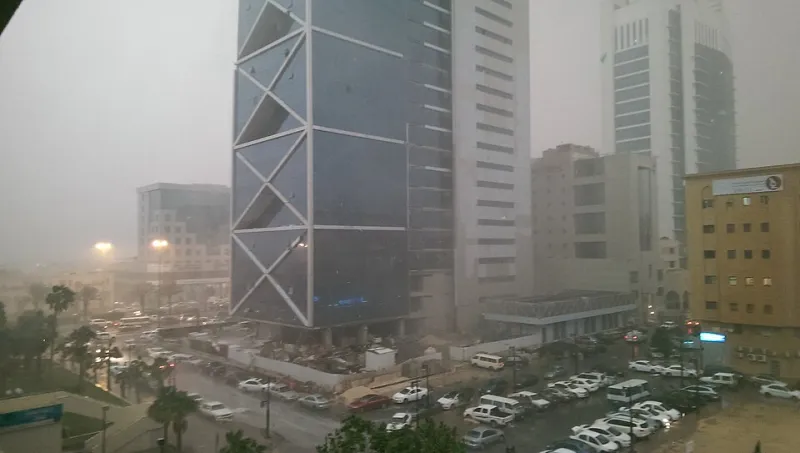
Photo: Mojackjutaily, CC BY-SA 4.0, via Wikimedia Commons
For decades, Saudi Arabia's real estate market operated largely as a domestic affair — a sector shaped by government land grants, tribal ownership customs, and a banking system that was only beginning to develop standardized mortgage products. That picture has changed dramatically. Fueled by Vision 2030's mandate to diversify the economy and expand homeownership, Saudi banks have built a financing infrastructure that is drawing the attention of institutional and individual investors from the United States alike.
The numbers justify the interest. Saudi Arabia's real estate sector is projected to reach a market size exceeding $69 billion by 2029, driven by mega-developments such as NEOM, the Red Sea Project, and Diriyah Gate. Behind each of these projects sits a complex web of financing arrangements — and American capital is increasingly finding its way into that web.
The Mortgage Market Comes of Age
As recently as a decade ago, mortgage lending in Saudi Arabia was a relatively underdeveloped segment of the banking sector. Home financing was often handled through government programs, and private bank participation was limited. Today, that landscape looks entirely different.
Major Saudi lenders — including Al Rajhi Bank, Saudi National Bank, and Riyad Bank — now offer a full suite of residential and commercial real estate financing products. Critically, these products are structured in accordance with Islamic finance principles, meaning they avoid conventional interest payments in favor of Murabaha (cost-plus financing) and Ijara (lease-to-own) arrangements.
For US investors accustomed to traditional mortgage structures, these instruments require some conceptual adjustment. Under a Murabaha arrangement, the bank purchases the property outright and resells it to the buyer at an agreed markup, with repayment spread over a fixed term. The economic outcome resembles a conventional mortgage, but the contractual framework is fundamentally different — a distinction that carries both legal and tax implications for American participants.
US investors considering direct property acquisition in the Kingdom should also be aware that foreign ownership rules, while liberalizing, still impose restrictions in certain zones and property categories. Working with a Saudi bank that has dedicated international client services is not merely convenient — it is often essential for structuring a compliant transaction.
Development Financing and the Infrastructure Opportunity
Beyond residential mortgages, the more significant opportunity for institutional American investors may lie in development financing. Saudi Arabia's gigaproject pipeline requires capital at a scale that domestic banks cannot fully absorb alone, creating openings for foreign co-financing arrangements.
Saudi banks have responded by structuring syndicated development loans and project finance facilities that allow international participants to take positions alongside domestic lenders. These structures are often underpinned by government guarantees or sovereign-linked offtake agreements, which meaningfully reduce the credit risk profile relative to comparable emerging-market real estate plays.
For US institutional investors — pension funds, family offices, and real estate private equity firms — these syndicated facilities offer exposure to Saudi real estate development without requiring direct property ownership, sidestepping many of the foreign ownership constraints that apply to individual buyers.
REITs: The Listed Route Into Saudi Property
Perhaps the most accessible entry point for American investors is Saudi Arabia's listed Real Estate Investment Trust market. The Kingdom's REIT sector, regulated by the Capital Market Authority (CMA), has grown steadily since its formal establishment in 2016 and now encompasses more than two dozen listed funds covering retail, hospitality, office, and residential assets.
Saudi REITs trade on the Saudi Exchange (Tadawul) and are subject to CMA governance requirements, including mandatory income distribution thresholds that will feel familiar to US investors accustomed to the domestic REIT framework. The key difference is that Saudi REITs are structured to comply with Shariah principles, meaning their underlying assets and financing arrangements must meet Islamic finance standards.
For US investors with access to international brokerage accounts or exposure through emerging-market funds that hold Tadawul-listed securities, Saudi REITs represent a liquid, regulated, and income-generating vehicle for real estate exposure. Dividend yields have historically been competitive relative to comparable instruments in Gulf markets, though investors should account for currency risk given that distributions are denominated in Saudi riyals — a currency pegged to the US dollar, which provides a degree of exchange-rate stability that is unusual in emerging-market real estate investing.
Regulatory Landscape: What Americans Must Understand
The regulatory environment governing foreign participation in Saudi real estate financing has evolved considerably under Vision 2030, but it remains more complex than equivalent frameworks in Western markets.
The Saudi Real Estate General Authority (REGA) oversees property registration and foreign ownership permissions. While reforms introduced in recent years have expanded the categories of property foreigners may own, restrictions persist in Mecca and Medina, and certain residential zones remain off-limits to non-Saudi nationals. US investors must conduct thorough due diligence on the specific asset class and geographic location before committing capital.
On the banking side, the Saudi Central Bank (SAMA) regulates mortgage lending and real estate financing products. SAMA's consumer protection framework has strengthened in recent years, but US investors should recognize that dispute resolution mechanisms differ from those available in American courts. Engaging legal counsel with expertise in both Saudi commercial law and cross-border investment structures is a practical necessity, not an optional precaution.
Tax considerations also warrant attention. Saudi Arabia imposes a Real Estate Transaction Tax (RETT) of 5% on property transfers, and while the Kingdom does not levy personal income tax on individuals, US citizens remain subject to American tax obligations on foreign income and capital gains regardless of where those gains are realized.
The Risk-Reward Calculation
Saudi Arabia's real estate market offers a genuinely compelling growth narrative — expanding urbanization, a young and growing population, government-backed demand stimulus, and a banking sector that has matured significantly in its ability to serve international investors. However, the risk profile is not without nuance.
Concentration risk is a real consideration: much of the current excitement is tied to a handful of megaprojects whose completion timelines and demand assumptions are subject to revision. Liquidity in the REIT market, while improving, does not yet match the depth of US or European listed real estate markets. And the political environment, while stable by regional standards, introduces a category of risk that requires ongoing monitoring.
For US investors willing to engage thoughtfully with these dynamics, Saudi Arabia's real estate financing ecosystem presents a differentiated opportunity — one that blends Islamic financial innovation, sovereign-backed development ambition, and a regulatory trajectory that is moving, if gradually, in the direction of greater openness to foreign capital.