Wealth Without a Payslip: How Saudi Arabia's Employment-Tied Banking System Penalizes Mobile American Professionals
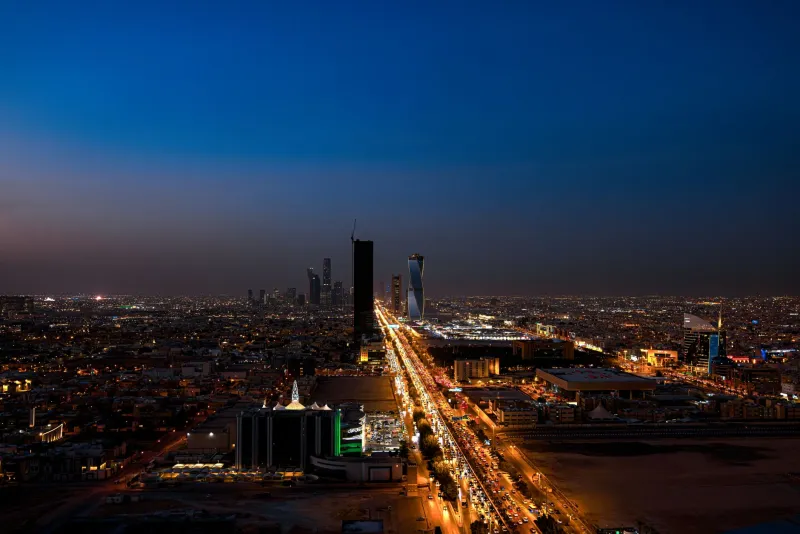
For most American professionals arriving in Saudi Arabia, the banking onboarding process feels straightforward enough — until it isn't. A salary certificate from a recognized employer, a valid Iqama, and a few weeks of patience will typically unlock a respectable current account, a debit card, and perhaps a modest credit facility. The system, in that sense, works.
But for a growing segment of the expat population — career changers, freelancers, early-stage entrepreneurs, and professionals on sabbatical — the same system quickly reveals a structural rigidity that has little patience for complexity. Saudi banks, by design, classify and reward customers primarily through the lens of employment status and salary level. When that lens doesn't apply cleanly, the consequences can be surprisingly severe.
Why Saudi Banks Think in Payslips
To understand the frustration, it helps to understand the logic. Saudi Arabia's banking regulatory framework, overseen by the Saudi Central Bank (SAMA), evolved alongside a labor market defined by formal employment relationships — particularly for expatriates, whose residency status is directly tied to employer sponsorship under the Kafala system. For decades, an expat's employer was effectively a proxy for their financial reliability. Banks built their risk models accordingly.
Salary transfer programs, known locally as Hafiz al-Rawatib arrangements, became central to how banks structured their product tiers. Customers who route their payroll through a given bank are rewarded with higher credit limits, preferential loan rates, waived fees, and access to premium banking tiers. Those who cannot demonstrate consistent salary inflows — regardless of their actual net worth — are treated as elevated risk by default.
The result is a system that is highly efficient for the majority of the expat workforce but structurally blind to anyone whose financial profile doesn't fit a single-employer, fixed-salary template.
The Career Changer's Dilemma
Consider a common scenario: an American professional who spent three years in Riyadh working for a multinational firm, built up a substantial investment portfolio, and then left that employer to launch a consulting practice or join an early-stage startup. On paper, their financial position may be stronger than before. In practice, Saudi banks may respond by downgrading their account tier, freezing credit facilities, or requiring an entirely new onboarding process with documentation requirements designed for salaried employees rather than self-employed individuals.
The problem is compounded by the fact that Saudi Arabia's regulatory environment for freelancers and independent contractors, while improving under Vision 2030 reforms, remains less mature than equivalent frameworks in the US or UK. Proof of income for the self-employed is harder to standardize, harder for bank compliance teams to verify, and therefore harder to accept as a substitute for a clean salary transfer record.
Entrepreneurs face a parallel challenge. Even if a business is generating meaningful revenue, the absence of a personal salary certificate — as distinct from corporate income documentation — can leave founders in a bureaucratic no-man's-land where neither retail banking products nor business banking solutions fully apply.
What the Tier System Actually Costs You
Being locked out of premium banking tiers in Saudi Arabia is not merely an inconvenience. The practical financial consequences are measurable. Basic-tier accounts frequently come with restrictions on international wire transfer limits, which matters enormously for expats managing cross-border finances between Saudi Arabia and the US. Credit card limits may be capped at levels that are inadequate for business travel or large purchases. Access to personal finance products, including home financing or vehicle loans, may be denied outright.
Perhaps most frustratingly, some banks apply these restrictions even when a customer holds substantial deposits with the same institution. Liquidity, in the Saudi banking tier model, is not always sufficient to substitute for income flow. The system rewards movement of money through payroll channels, not the static accumulation of savings.
Workarounds That Actually Function
For Americans caught in this bind, several practical strategies are worth evaluating — ideally before a career transition occurs rather than after.
Maintain your existing banking relationship through the transition. If you are moving from salaried employment to self-employment or entrepreneurship, try to negotiate a grace period with your bank before salary transfers cease. Some relationship managers, particularly at larger institutions such as Al Rajhi Bank, Riyad Bank, or Saudi National Bank, have discretion to maintain account tiers for established customers during documented transitions.
Leverage wealth-based private banking thresholds. Several Saudi banks offer private banking or priority banking tiers that are triggered by asset levels rather than salary volumes. If your combined deposits, investments, or portfolio value can meet the minimum threshold — which typically ranges from SAR 500,000 to SAR 1,000,000 depending on the institution — you may be able to access premium services through a wealth-based relationship rather than an employment-based one.
Consider international banking alternatives. For expats whose Saudi banking needs are primarily transactional, maintaining a robust US-based account with strong international capabilities — such as those offered by Charles Schwab or Citibank's global network — and using a Saudi account solely for local spending can reduce dependence on Saudi tier classifications. This approach sacrifices local credit access but preserves operational flexibility.
Explore digital banking options. Saudi Arabia's newer digital banks, including stc bank and others operating under SAMA's open banking framework, have in some cases adopted more flexible income verification approaches that may accommodate non-traditional employment arrangements better than legacy institutions.
The Regulatory Rationale — and Its Limits
It is worth acknowledging that SAMA's conservatism in this area is not arbitrary. Saudi Arabia's banking system has historically maintained strong stability metrics in part because its credit standards are tightly controlled. The salary-transfer model reduces default risk in a market where expatriate residency can be revoked, making it genuinely difficult for banks to recover losses from individuals who have left the country.
Nonetheless, as Vision 2030 actively courts international entrepreneurship, encourages foreign investment, and attempts to build a startup ecosystem, the tension between these regulatory defaults and the needs of a more mobile professional class is becoming harder to ignore. SAMA has signaled awareness of this friction through its open banking and fintech licensing initiatives, but meaningful reform to how non-salaried expats are classified within retail banking frameworks has been slow to materialize.
Planning Ahead Is the Only Real Protection
For American professionals considering a career transition while based in Saudi Arabia, the most important advice is to treat banking strategy as part of the professional planning process — not an afterthought. The window between leaving a formal employer and being reclassified by your bank may be shorter than expected, and the bureaucratic path back to premium status can be lengthy.
Understanding where you stand in your bank's tier structure, what documentation would be required to maintain that standing under self-employment, and what alternative institutions might offer more flexibility are all questions worth answering before a career move rather than after. In a banking system built around the payslip, the professionals who fare best are those who plan for the moment the payslips stop.