The Cost of Comfort: How Familiar Money Transfer Habits Are Quietly Costing American Expats Thousands Each Year
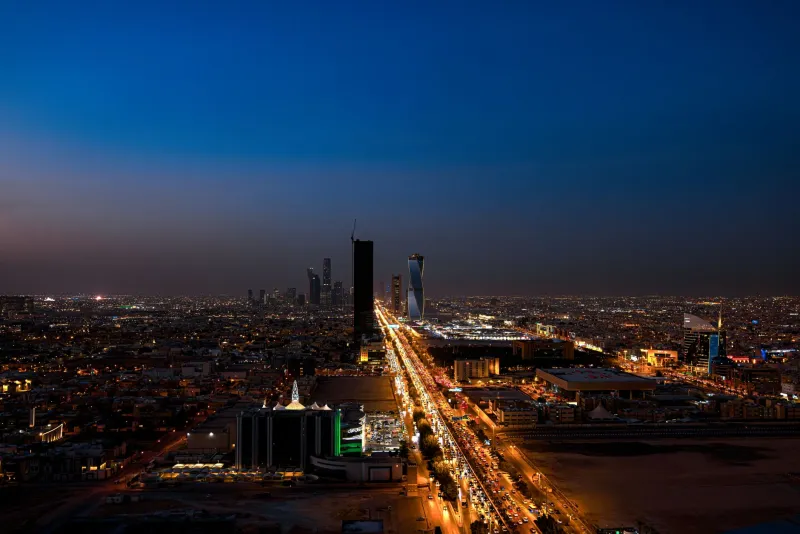
For many Americans working in Saudi Arabia and supporting family members back home — or sending funds to relatives elsewhere in the region — the monthly remittance has become as routine as paying rent. Open an app, enter an amount, confirm the transfer. Done. What rarely gets examined is the line between what the sender intended to send and what the recipient actually receives. That gap, multiplied across twelve months, often runs into the thousands of dollars.
This is not a story about fraud or negligence. It is a story about comfort, inertia, and the surprisingly high price of doing what feels familiar.
How the Habit Forms
When American professionals arrive in Saudi Arabia — whether recruited by an energy company, a financial institution, or one of the Kingdom's many Vision 2030 infrastructure projects — their employer frequently assists with the banking setup. A local Saudi bank account is opened, sometimes with preferred corporate rates attached, and the employee is handed a debit card and a set of instructions. Remittances often begin through whatever mechanism the bank recommends or whatever app the expat already had installed on their phone.
The result is a financial inertia that proves remarkably durable. According to financial advisors who work with expatriate communities in Riyadh and Jeddah, a significant portion of their American clients have been using the same transfer method for two or more years without ever benchmarking it against alternatives.
"The setup phase is where the habit gets locked in," explains one Riyadh-based wealth consultant who works primarily with US and European expats. "People are focused on housing, schooling for their kids, getting their bearings in a new country. Optimizing their wire transfer app is the last thing on their minds. And then it just never becomes a priority."
What the Numbers Actually Look Like
Consider a common scenario: an American professional earning a SAR-denominated salary of approximately 25,000 SAR per month sends the equivalent of $2,000 USD to a family member in the United States each month. Over the course of a year, that amounts to $24,000 in total transfers.
A major US bank or a well-known consumer transfer app might apply an exchange rate markup of 2.5 to 4 percent above the mid-market rate, in addition to a flat transaction fee ranging from $5 to $35. On a $2,000 monthly transfer, even a 3 percent markup translates to roughly $60 in hidden costs per transaction — or $720 annually — before factoring in flat fees. For those sending larger amounts, the figures scale accordingly.
By contrast, several specialist remittance platforms operating in the Saudi-to-US corridor have been documented charging markups below 0.5 percent with flat fees under $5. The same $24,000 annual transfer volume processed through one of these services could reduce total transfer costs to under $200 for the year — a saving of $500 or more compared to a mid-range traditional service, and potentially $1,500 or more compared to the most expensive options.
For expats supporting multiple family members, or those managing larger monthly transfers common among senior professionals, the savings differential can comfortably exceed $3,000 to $5,000 annually.
The Platforms Most Expats Overlook
The remittance technology landscape has evolved considerably over the past five years, yet awareness among American expats remains uneven. Several platforms have built efficient USD-SAR and SAR-USD corridors with competitive rate structures that go largely unnoticed by users anchored to legacy services.
Wise (formerly TransferWise) remains one of the most widely cited alternatives among financially literate expats, offering mid-market rate transfers with transparent fees. However, it is far from the only option. Platforms including Remitly, OFX, and certain regional fintech services licensed by the Saudi Central Bank (SAMA) have developed competitive offerings specifically for the Gulf-to-US and US-to-Gulf corridors.
It is worth noting that not all platforms serve all transfer directions with equal efficiency. Some services that are highly competitive for USD-to-SAR transfers perform less favorably in the reverse direction. Expats should benchmark both directions independently, particularly if they receive salary in Saudi riyals and make transfers in both directions across a calendar year.
The Psychology of Switching
If the financial case for switching is so clear, why do so many American expats continue using more expensive services? The answer involves a convergence of psychological factors that behavioral economists have studied extensively in other consumer finance contexts.
First, there is the trust heuristic. Established banks and household-name apps carry an implicit credibility that newer platforms have not yet earned in the minds of many users. The fear that a transfer might fail, arrive late, or become entangled in compliance issues is a powerful deterrent — even when the statistical risk is minimal with licensed, regulated providers.
Second, the cost is invisible in a way that, say, a high monthly fee on a checking account is not. Exchange rate markups do not appear as line items. They are embedded in the rate itself, making the loss abstract and easy to ignore.
Third, the switching effort, while objectively modest — typically involving account verification, identity documentation, and a test transfer — feels disproportionately burdensome to people who are already managing the logistical complexity of expatriate life.
"I knew I was probably overpaying," said one American engineer based in Dhahran who eventually switched providers after a colleague ran the numbers for him. "But every time I thought about setting up a new account, something else came up. It took my friend sitting down with me and showing me the actual dollar figure before I finally did it."
Employer-Sponsored Banking: A Double-Edged Arrangement
Many large employers in Saudi Arabia — particularly in the oil and gas sector — negotiate preferred banking arrangements with domestic Saudi banks on behalf of their expatriate workforce. These arrangements often include waived account fees, priority service, and streamlined payroll processing. They are genuinely valuable.
However, the remittance services attached to these employer-preferred banks are rarely the most competitive available. Corporate banking relationships are negotiated with a different set of priorities than retail transfer efficiency, and the remittance component is seldom the focal point of those negotiations.
Expats are generally free to use any licensed transfer service they choose, regardless of their employer's preferred banking partner. The salary can be received through the employer-designated account and then transferred outward through a more cost-efficient platform. The two decisions — where to receive salary and how to remit funds — need not be linked.
A Practical Framework for Reducing Transfer Costs
For American expats looking to audit and improve their remittance strategy, a structured approach yields the clearest results.
Step one is establishing a baseline. Review the last three to six months of transfer records and calculate the effective exchange rate received on each transaction. Compare this to the mid-market rate for the same dates, available through sources such as xe.com or the SAMA official rate publications. The difference, expressed as a percentage, is your current markup cost.
Step two is benchmarking. Run a comparison across at least three alternative platforms for a hypothetical transfer matching your typical amount and direction. Most platforms provide instant quotes without requiring account creation.
Step three is a controlled pilot. Select the most competitive platform that is licensed and regulated in a recognized jurisdiction, complete the verification process, and execute one transfer. Verify the recipient experience — speed, accuracy, ease of receipt — before committing to a full transition.
Step four is scheduling a periodic review. Transfer costs and platform competitiveness shift over time. A service that leads the market today may not do so in eighteen months. Building a quarterly review into your financial routine ensures that inertia does not re-establish itself.
The Broader Implication
The remittance habits of American expats in Saudi Arabia represent a microcosm of a broader pattern in personal finance: the tendency to optimize large, visible decisions while neglecting recurring, semi-invisible costs. A professional who would spend hours negotiating a salary package or comparing mortgage rates may spend fewer than ten minutes selecting the service through which they will send tens of thousands of dollars over the course of a year.
The Kingdom's increasingly sophisticated financial infrastructure, combined with SAMA's ongoing regulatory modernization, has created conditions in which competitive, reliable, and cost-efficient transfer services are genuinely accessible to American expats. The opportunity exists. The question is whether the habit of comfort will continue to stand in its way.