When Marriages End Abroad: Navigating the Financial Fallout of Divorce Across Saudi and US Banking Systems
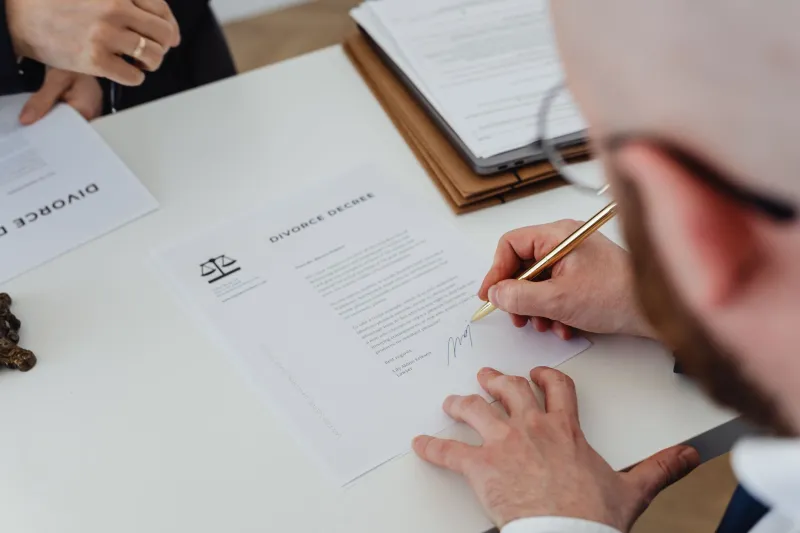
For American professionals living and working in Saudi Arabia, the Kingdom offers considerable financial rewards: competitive tax-free salaries, generous housing allowances, and access to a rapidly modernizing banking sector. Yet the same cross-border financial architecture that makes expat life so lucrative can become extraordinarily complicated when a marriage dissolves. Divorce between an American and a Saudi national — or even between two American expats residing in the Kingdom — triggers a cascading series of legal and financial consequences that span two jurisdictions, two banking systems, and two fundamentally different legal philosophies.
Understanding those consequences before they arrive is not pessimistic. It is prudent.
Two Legal Systems, One Financial Life
Saudi Arabia operates under Islamic law, known as Sharia, which governs family matters including marriage, divorce, and inheritance. The United States, by contrast, applies a patchwork of state-level family law frameworks that vary considerably depending on whether a state follows community property rules or equitable distribution principles.
When an American expat divorces in Saudi Arabia, neither system simply defers to the other. Saudi courts have jurisdiction over marriages that took place or were registered within the Kingdom, and they apply Sharia principles to asset division, custody determinations, and spousal financial obligations. Meanwhile, US courts may assert their own jurisdiction — particularly if one spouse returns to American soil — leading to parallel proceedings that can produce conflicting rulings.
This jurisdictional tension is not theoretical. American expats have found themselves subject to Saudi court orders that US courts do not recognize, and vice versa. The financial consequences of that gap can be severe.
What Happens to Bank Accounts During Divorce Proceedings
One of the most immediate financial risks in an international divorce is the freezing or restriction of bank accounts. In Saudi Arabia, it is not uncommon for a party to a divorce proceeding to petition the court to place a hold on joint accounts or even individual accounts held in the other spouse's name, particularly where there is a dispute over marital assets or pending financial claims.
For American expats whose primary income flows through a Saudi bank account — whether at Al Rajhi Bank, Saudi National Bank, or one of the Kingdom's newer digital banking platforms — a court-ordered account restriction can halt salary deposits, block bill payments, and disrupt remittances to the United States entirely. This is especially problematic for expats who have structured their finances around a single Saudi account, with limited liquidity held domestically.
Expats in dual-income households where both spouses hold accounts at the same institution face additional exposure. Saudi banks are obligated to comply with judicial orders, and the timeline for resolving account restrictions through the court system can stretch from weeks to several months.
Asset Division Under Sharia: What Americans Often Misunderstand
Under Sharia-based divorce law in Saudi Arabia, the concept of marital property division differs substantially from the American model. In the US, divorcing spouses typically divide assets accumulated during the marriage, with the precise methodology depending on state law. In Saudi Arabia, the default position under Sharia is that each spouse retains ownership of assets held in their individual name.
At first glance, this might seem advantageous to an American expat who has maintained separate accounts. However, the reality is more nuanced. Mahr — a mandatory financial gift from husband to wife stipulated in the Islamic marriage contract — becomes immediately payable upon divorce if it has not already been paid. Depending on the terms of the marriage contract, this obligation can be substantial.
Additionally, Saudi courts may order nafaqa, a form of financial maintenance that the husband is obligated to provide to the wife and children following divorce. The calculation of nafaqa takes into account the husband's income and standard of living, meaning that a well-compensated American expat may face maintenance obligations that significantly exceed what a US family court might have ordered.
For American expats who entered into marriage contracts without fully understanding these financial provisions — or without independent legal counsel — the financial exposure can be considerable.
Cross-Border Custody and Its Financial Implications
Custody disputes in international divorces carry their own layer of financial complexity. Saudi family law generally favors maternal custody for young children, with custody transitioning to the father at specified ages. However, the Kingdom also restricts the ability of children holding Saudi nationality to leave the country without the father's consent, regardless of where the mother is from.
For an American mother seeking to return to the United States with her children following a divorce, this restriction can create a prolonged and expensive legal battle. Legal fees, travel costs, and the expense of maintaining two households across continents can drain financial resources rapidly. Meanwhile, child support obligations may be governed simultaneously by Saudi court orders and US state court determinations — which do not always align in terms of amount or enforcement mechanisms.
American fathers in Saudi Arabia face a different but equally complex set of challenges if a Saudi spouse seeks to relocate children domestically or restrict access. Enforcement of US custody orders in Saudi Arabia is not guaranteed, and navigating the Kingdom's family court system without fluency in Arabic and familiarity with local legal practice is exceptionally difficult.
Protecting Yourself Before a Crisis Emerges
Financial preparedness in the context of international marriage is not about anticipating failure — it is about ensuring that a worst-case scenario does not become a permanent financial catastrophe. There are several practical steps American expats in Saudi Arabia can take to reduce their exposure.
Maintain independent financial accounts in both countries. Relying exclusively on a Saudi bank account for all financial activity creates unnecessary vulnerability. Keeping an active US account — ideally at a bank with international capabilities and no foreign transaction fees — ensures access to funds regardless of what happens to accounts held in the Kingdom.
Understand your marriage contract in full. Islamic marriage contracts are legal documents with direct financial consequences. Before signing, every term — including the mahr amount, any deferred financial obligations, and conditions governing divorce — should be reviewed by an attorney licensed in both Saudi and US law.
Document assets held in both jurisdictions. In the event of divorce proceedings, clear documentation of pre-marital assets, inheritance, and individually owned property can be critical in preventing those assets from becoming subject to dispute.
Consult a cross-border family law attorney early. Attorneys who specialize in international family law, particularly in the Gulf region, can provide guidance that generic US divorce attorneys are not equipped to offer. The cost of that consultation is modest compared to the financial risk of proceeding without it.
Review beneficiary designations and power of attorney arrangements. Life events that alter the nature of a relationship should prompt an immediate review of all financial documents, including wills, account beneficiaries, and any powers of attorney that may have been granted to a spouse.
A Situation That Demands Early Attention
The financial systems of Saudi Arabia and the United States were not designed with cross-border divorce in mind. The intersection of Sharia family law, US state-level divorce statutes, international banking regulations, and competing jurisdictional claims creates a landscape that is genuinely difficult to navigate — even for financially sophisticated individuals.
American expats who approach their time in the Kingdom with the same strategic thinking they apply to their careers and investments will be far better positioned to manage whatever life circumstances arise. That means treating cross-border financial planning not as a luxury, but as an essential component of living and working abroad.